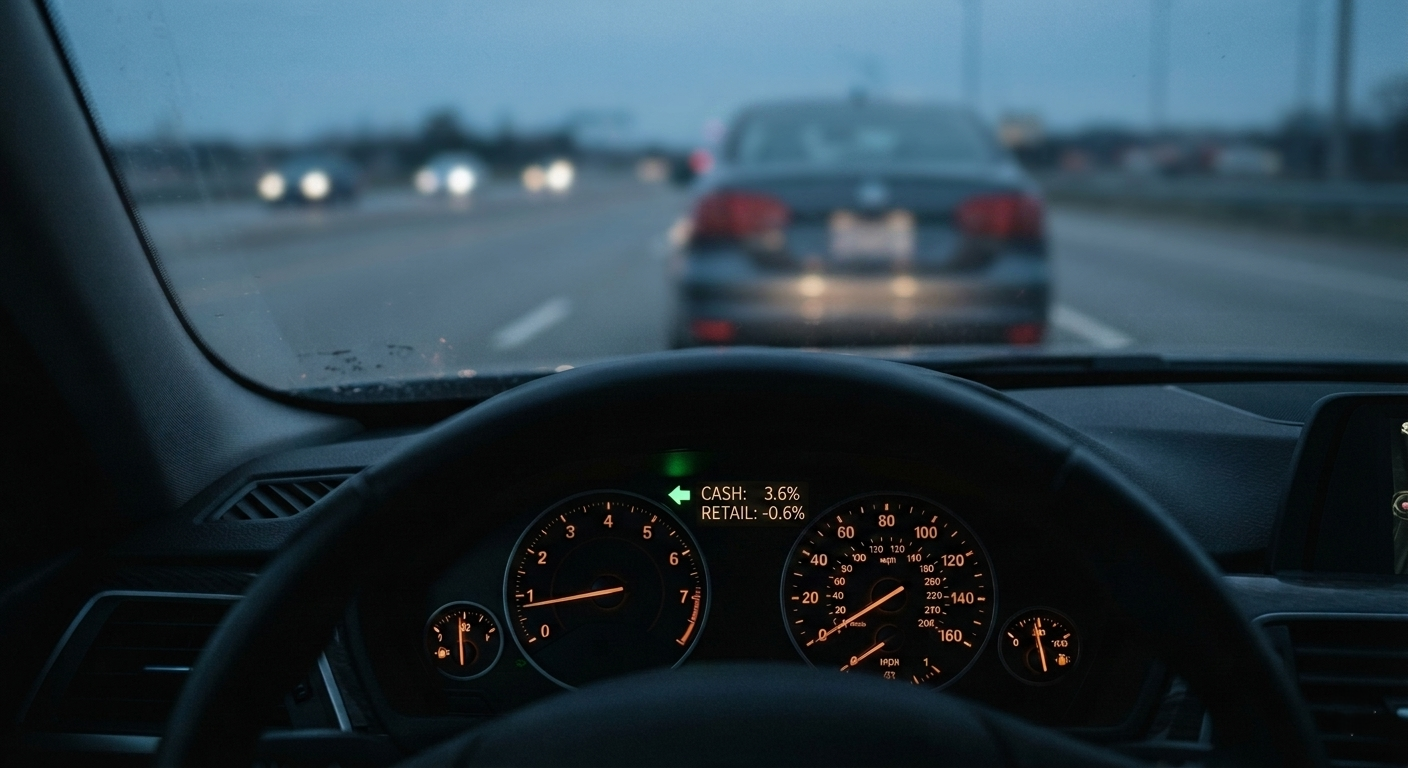
Imagine your car's turn signal. The blinker. You flip it before you turn, not after — it tells the people around you where you're headed next.
This week, government data came out telling the world where consumers are headed. Smart money went the opposite direction.
Start with prices. The Consumer Price Index, released Tuesday, rose just 0.1% for the month. A year ago, prices were climbing 3.4%. Now the yearly pace has slowed to that same number, and it's still cooling. Wednesday brought the Producer Price Index — a measure of what businesses pay each other, before those costs show up on a store shelf. It didn't move at all. Flat. Then Friday, retail sales. Americans spent 0.6% less at stores and restaurants in July than they did in June. Prices were still edging up that same month, which means this wasn't just less money going out the door. People bought fewer things, period.
Three reports. Three separate agencies. One direction: slower.
The retail sales pullback wasn't evenly spread. A look at where the weakness actually landed:
Retail sales by category, month-over-month change, July 2026. Source: U.S. Census Bureau, Advance Monthly Retail Trade Survey.
Now look at where professional money went the same week. Bank of America's monthly survey of global fund managers — hundreds of people overseeing hundreds of billions of dollars — found cash holdings had dropped to 3.6%, the lowest level since February. Low cash means high confidence. These are people paid to read the economy before the rest of us do, and in July, they read it as a green light. It's the most aggressively positioned this group has been in five months.
Institutional cash levels (BofA Fund Manager Survey) vs. Census retail sales, month-over-month, May–July 2026. Sources: BofA Global Fund Manager Survey; U.S. Census Bureau, Advance Monthly Retail Trade Survey.
Professional investors aren't necessarily wrong here. Markets move on more than three data points, and money managers are often looking further down the road than a single month of numbers. The government reports aren't wrong either — cooling growth after a hot stretch is often exactly what a healthy economy is supposed to do. Neither side has to be lying for both of these things to be true at once, and that's what makes the gap worth noticing instead of explaining away.
Because most people don't get to choose which signal they respond to. A fund manager can shift a portfolio in an afternoon based on next week's Federal Reserve meeting. A family deciding whether to take on a car payment, or whether this is the month to finally fix the roof, is reading the same slowdown in retail sales and drawing the only conclusion available to them: things feel tighter, so hold off. They don't have a second signal telling them the smart money still likes the odds. They only have the one flashing in front of them — their own paycheck, their own bills, their own grocery total — and right now, that one says caution.
That's the cost of an economy running two signals that don't agree. When they split like this, most people don't have the luxury of waiting to see which one turns out to be right. They live with whichever one is currently telling them the truth about their own life. A fund manager who guesses wrong on a signal absorbs a bad quarter. A family who guesses wrong absorbs a bad year — sometimes worse, since there's no next allocation to fix it with — not because they read the data wrong, but because the system still has no way to connect what the economy is doing to what people are actually able to buy.
None of this means smart money is smarter than it looks, or that the consumer knows something Wall Street doesn't. It just means two different groups looked at the same week and came away with two different answers. When that happens, the honest thing to do is say so plainly, and let people draw their own conclusions about which signal they trust.
This is where the National Productivity Unit — NPU — fits in. It wouldn't tell a fund manager or a family which signal to trust this month. What it would do is put a public number next to the private ones — a plain way to check whether pay and cost are actually moving together, so a family reading caution in their own bills isn't left guessing whether that caution is backed up by anything beyond a bad feeling. Two signals disagreeing isn't the problem by itself. Not having a third, public signal built for the people without a portfolio to hedge with — that's the piece still missing.